Boundary energy, local inverses, and harmonic data
A boundary condition plays two distinct roles. It selects an energy space before a solution has pointwise values, and it removes one of the normal modes in a local solver. We develop both roles and connect them through a regularity argument that starts with only one derivative. The harmonic case then turns interior solutions into operators acting on boundary data.
The order of construction is intentional: weak existence does not depend on boundary smoothness; regularity does. A separate normal-mode calculation records the precise extension from real to complex quadratic principal symbols. Higher-order systems and arbitrary boundary conditions require their own complementing-condition theory.
1. Spaces, conventions, and exact entry contracts
Put , and use with inverse factor . Thus . Inner products are linear in the first variable. On , For an integer , denotes the space of functions with all weak derivatives through order in . On a half-space it is the restriction of the whole-space space, with equivalent norm; a proof appears below. For nonintegral , the restriction space carries the quotient norm. We write for the boundary trace and for the exterior unit normal. An equation with Lipschitz leading coefficients and an initially solution uses the weak multiplication rule from Section 7 of Local inverses and distance-weighted elliptic estimates: .
The next four groups of facts identify exactly what the arguments use.
- Fourier and Sobolev facts. Fourier inversion and Plancherel extend to all of , with the normalization (B1); Fourier transformation commutes with weak derivatives. The full-space extension is the initial Plancherel paragraph in the proof in Section 5 of Two measuring scales, one Weyl product (no selfadjoint-generator result from that item is needed). Its argument, from the Schwartz identity in Section 2 of Fourier transforms, finite spectra and convex separation, is: an isometry on a dense subspace extends to its completion, and its dense image is closed and therefore all of . The same argument gives partial Fourier transformation with an additional variable, first on finite sums of product functions and then by density. Weighted completions define (B1). No pointwise Fourier transform is required for a general function.
- Weak derivatives and localization. The integration, weak-derivative, smooth approximation, and Lipschitz product results in Local inverses and distance-weighted elliptic estimates are used with . Smooth changes of variables on compact coordinate patches, finite partitions of unity, and finite-dimensional linear algebra are entry facts. We supply below the precise Sobolev consequences of boundary flattening that are needed here.
- Local elliptic inverses. Section 2 of Local inverses and distance-weighted elliptic estimates supplies a fundamental solution for any homogeneous elliptic scalar polynomial, local bounds for convolution through its order, and the two convolution inverse identities on their stated domains. Section 7 of Local inverses and distance-weighted elliptic estimates supplies the Lipschitz commutator, and Section 8 of Local inverses and distance-weighted elliptic estimates supplies interior regularity from an solution with principal part. Our boundary argument proves the additional trace and reflection assertions instead of treating the interior theorem as a boundary theorem.
- Boundary operator calculus. Only the layer-potential portion uses the order operators, local quantization, Sobolev mapping, and smooth compact-manifold assembly proved in Symbols, operators and Sobolev scales and Detecting regularity without choosing coordinates, and compact-perturbation Fredholm theory in Finite defects under perturbation. The particular kernels, jumps, and boundary data spaces must still be checked below.
All Sobolev estimates are complex-linear unless an energy argument explicitly assumes a real symmetric positive coefficient matrix. Bounds may depend on a fixed coordinate patch and coefficient bounds. A local inverse makes no assertion of uniqueness without conditions on the rest of the boundary.
2. Traces, lifts, and a boundary-free energy domain
Write , . The following elementary estimate is the source of the half derivative at the boundary. For a smooth scalar function decreasing at infinity, Indeed integrate and use . The same inequality holds for an function on the ray by approximation, or by choosing a sequence tending to infinity on which its value tends to zero. Integrating (B2) in proves Here and below the assertion about slices refers to their continuous representative, not to an arbitrary representative on sets of measure zero.
We justify the approximation and the weak-space interpretation. If , testing against products of a test function in and one in gives the one-dimensional weak derivative identity for almost every tangential slice. A one-dimensional function with integrable weak derivative equals an absolutely continuous primitive plus a constant: subtract its integral primitive; the remaining distribution has derivative zero, as follows by testing against the derivative of every compactly supported test function of integral zero. Reflecting this representative evenly across zero therefore gives an function. Its tangential derivatives are even reflections and its normal derivative is the signed reflection of ; integration by parts on the two rays cancels the boundary terms. Fubini yields a bounded even extension on . Whole-space convolution and cutoffs now give approximation by restrictions of . This proves both the weak-derivative characterization of the restriction space and the density used in (B3). The case has no tangential variable and uses exactly the same one-dimensional argument.
For smooth approximants the map is continuous into . Bound (B3) makes these maps uniformly Cauchy on the closed ray, proving bounded continuity for every function. In particular is bounded. More generally, for every integer , are bounded maps with . To prove the trace bound, apply (B2) after multiplying by ; the two resulting integrals are controlled by the tangential derivatives of orders at most and their first normal derivatives. For the lift, each derivative of total order has squared integral at most , because . This proves (B4), including its inhomogeneous low frequencies.
For completeness, the restriction and weak norms agree at every integer . On the negative ray set , choosing the unique solution of , . The matrix is Vandermonde. Derivatives through order match at zero; repeated integration by parts introduces no interface delta through order . Change of variable on each reflected term bounds the extension in . Smooth approximation follows by this extension and convolution. In particular tangential differentiation commutes with the trace whenever the indicated derivatives lie in .
Let be extension by zero. Integration by parts, first on smooth approximants and then using (B3), gives the distribution identities Consequently if and only if . For necessity, an function cannot be a nonzero distribution supported on a hyperplane: that hyperplane has Lebesgue measure zero. Conversely (B5) lists all its first derivatives as functions. These formulas also show why a nonzero boundary value cannot simply be extended by zero in an energy argument.
For any bounded open , define identifying its elements with their restrictions to . Every such element vanishes almost everywhere outside . This is the homogeneous Dirichlet domain, even when the boundary is irregular. Multiplication by a smooth function with bounded value and first derivatives preserves it, by the product estimate and approximation.
If is , three descriptions agree: (B6); functions in with zero local flattened trace; and functions supported in . Here is the local-to-global proof. A flattening and its inverse have bounded first derivatives and Jacobians on a smaller compact patch. The chain rule and change of variables bound composition in , initially for smooth functions and then for weak functions by approximation. A zero-trace function extends by zero across the flattened plane by (B5). Translate that extension a distance into the upper half-space and convolve at radius less than ; after a fixed smaller cutoff this gives smooth functions supported strictly on the interior side, converging in . Pulling them back gives compactly supported functions in ; ordinary convolution at a distance smaller than their distance from the boundary approximates each by . A finite partition of unity and interior convolution prove inclusion in (B6). Conversely (B3) and the composition estimate give zero trace for limits of tests. Finally a whole-space function supported in has identical traces from both sides of each flattened plane, by the slice continuity proof; its exterior trace is zero and so is its interior trace. A boundary has measure zero, since finitely many graph patches have measure zero by Fubini. Thus there is no additional function carried only by the boundary. No support characterization for an arbitrary irregular domain has been used.
Inhomogeneous Dirichlet data is removed by a lift, not by a pointwise substitution without a function-space bound. If on a flat boundary and , then Bounded coefficients suffice for . For a divergence-form energy equation the corresponding lift is , and the adjusted forcing is a continuous functional on , generally in , not necessarily . Smooth compact-boundary lifts are obtained from (B4) in charts and a partition of unity. At regularity , meaning that the first chart derivatives are Lipschitz, the same assertion holds: integer composition uses the bounded weak second derivatives of the charts, while the boundary norm is plus the half-order norm of first derivatives. That half-order norm is equivalent to , as Fourier transformation and the substitution show. Bi-Lipschitz changes of variables preserve this integral up to constants, and multiplication by a bounded Lipschitz function is bounded in it after separating differences and integrating near and away from the diagonal. These facts justify the stated chart norm without assuming a smooth boundary at this step.
3. The energy solution before boundary regularity
Let be bounded and open. Assume is real, symmetric, continuous on , and positive definite at every point there. Compactness supplies constants with For complex , apply the real inequality to real and imaginary parts; symmetry cancels their imaginary cross terms. Define Then for every there is exactly one satisfying The equation holds distributionally, and no boundary regularity is assumed.
Proof. Translate coordinates so that on . For a compactly supported test function, integrate over the whole space. Cauchy-Schwarz gives Equivalently, before bounding , one has . Density extends these bounds to . Hence is a norm equivalent to its complete norm, and .
We give the minimization argument, including existence, instead of leaving a representation theorem implicit. Set . Its infimum is finite because is bounded below. A minimizing sequence is bounded in the norm. The parallelogram identity gives It is therefore Cauchy and converges in to a minimizer . For real , differentiating the quadratic polynomial at zero gives the real part of (B10). Applying it to gives the imaginary part. Set and use the functional bound to obtain , hence (B10). The difference of two solutions has zero norm. Testing (B10) on is exactly the distributional equation. Conversely that equation for an element of extends to every by density and the continuity of both sides. This proves the equivalence as well as uniqueness.
The proof also applies to any continuous conjugate-linear forcing functional on , with its dual norm replacing . Thus (B7) gives weak existence for lifted boundary values on a regular boundary, and a different lift gives the same solution because their difference belongs to .
The complete dual norm and measurable coefficients. The same proof needs only an essentially bounded measurable real symmetric matrix satisfying every bound in (B8) almost everywhere, with the stated constants . Pointwise real symmetry gives the complex inequality; diagonalizing the actual finite symmetric matrix shows . Thus , and . These estimates, (B11), completeness of (B6), and the exact identity (B12) prove existence and uniqueness for every bounded conjugate-linear by replacing by in the entire minimization argument. This extends weak existence; the later regularity theorems retain their additional coefficient hypotheses.
Retain both norms of the forcing on this same space. Set , using the actual coordinate bound in (B11). Its proof gives . The two unit-ball inclusions and homogeneity then give Testing proves, for , ; division is legitimate by (B11). For the same bounds hold directly. Consequently the full constants are For an actual lift , the forcing for is exactly . It is bounded by . If another lift is , with , its solution is , since substitution gives . Adding the respective lifts proves equality of the resulting original .
Sergio Vessella’s freely accessible original-author notes, arXiv:2305.04765v1, give the variational construction in Chapter 4, Sections 4.1–4.3. The exact comparison in Dirichlet lifting and the full dual norm, (VE1)–(VE26), proves the isometry of its closure space with (B6), compares its original constants with (B8), and supplies complete counterexamples for the printed lifting sign and the printed estimate stab when its specified full dual norm is used. The source correction is identified there as editorial material. Here (B7) and (BO7)–(BO8) retain the negative lifted form and the required norm factors.
Example: an elliptic coefficient without classical first derivatives everywhere. In a ball take . It is continuous, Lipschitz, and uniformly positive. Formula (B10) defines a unique energy solution. Expanding its operator produces the first-order coefficient in front of , defined almost everywhere. A theorem requiring continuous lower-order coefficients would not apply to this expansion. The bounded-lower-coefficient regularity theorem below does.
4. A reflected solver and its two inverse identities
Let be a real homogeneous elliptic quadratic polynomial, and write for its positive signed comparison. Its quadratic form is definite: on the connected unit sphere for , a nonzero continuous real function has constant sign; for the assertion is immediate. Choose so that is positive. It can be reduced to by a linear change preserving the plane and its positive side. Indeed write , where . Completing the square leaves the positive Schur complement . A tangential shear removes ; a positive normal dilation and an invertible tangential change normalize the remaining blocks. The dual physical transformation has last coordinate a positive multiple of . All derivative and measure norms are equivalent under this fixed change. The reflected calculation below uses coordinates in which . The exact signed comparison with the original form follows.
Here is the exact map back to the original form, including its sign and volume factor. Retain the original , its sign , the positive comparison , and the displayed . Put The matrix is positive definite: for nonzero , evaluate the positive form at to get . The exact square and transformed full symbol are For , is the empty matrix and . The inverse coordinates are and . Thus carries the upper half-space onto itself and the boundary plane onto itself. The chain rule gives Indeed the exact derivative maps are and . Substituting both into the displayed full square gives , including the normal dilation and every mixed term. If is the reflected construction’s whole-space fundamental solution, the original fundamental solution is To verify the factor, change variables in a test pairing: the Jacobian cancels , the two factors of multiply to one, and . On a transformed local patch, the original right or left inverse is , with the same support restrictions transported by . All constants in its Sobolev bounds retain their dependence on this fixed map. This conjugation carries every original coefficient through the Laplacian calculation.
Fix a bounded ball centered on the plane and invariant under reflection. For , let equal on , its negative reflection on , and zero elsewhere. Choose an exact fundamental solution of that is even in . Such a solution is obtained by averaging the solution of Section 2 of Local inverses and distance-weighted elliptic estimates with its reflected distribution. Convolution with , restricted to , defines The local convolution bounds of Section 2 of Local inverses and distance-weighted elliptic estimates give For the trace, convolution is odd because is even and is odd; it is locally , so the two one-sided traces agree and oddness forces them to vanish. The convolution bounds are local; a global inverse of the homogeneous Laplacian has not been asserted.
There is also the distinct left identity To verify it, reflect oddly. The function is continuous at the plane. Its first normal derivative is the even reflection of , so it too is continuous there. Thus the second normal derivative has no interface delta. Tangential differentiation does not differentiate the sign of , and tangential derivatives of the zero trace vanish. Therefore ; the compared Laplacian has no mixed normal-tangential monomials, and the full original operator is recovered by the proved conjugation. Compact support permits transferring in the convolution, yielding . This proves (B15).
The same reasoning proves a useful density fact. If has zero trace and compact support up to the plane, its odd extension is . The only possible interface term would be the jump of a first derivative. The normal derivative is even, and the tangential derivatives have zero trace by Section 2. Convolving this extension with an even smooth mollifier produces smooth odd functions converging in ; a symmetric cutoff keeps their supports in any prescribed slightly larger neighborhood. Consequently (B15) and its norm estimate extend to such functions whenever their support lies in the fixed patch.
5. Continuous principal coefficients and a local inverse
Let near zero. Suppose the principal coefficients are continuous, their frozen quadratic polynomial is real elliptic, and the lower-order coefficients are locally essentially bounded. Then a sufficiently small neighborhood has a bounded linear map with The original continuous-coefficient situation is included. Products in are products, since .
Proof. Make the boundary-preserving normalization above and work on a fixed unit patch in the rescaled variable . Multiplying the equation by gives a frozen principal operator and perturbation By (B14), . Choose making this norm at most , put , and set The series converges in operator norm, gives a two-sided inverse, and has norm at most two. Since , the right identity and trace assertion follow. For a compact smooth zero-trace , put . Identity (B15) gives , and hence . Applying (B19) yields the left identity. Rescaling back gives (B17) and boundedness of every derivative through order two. Explicitly the scaled bound is . No smallness of unscaled lower-order coefficients was assumed.
In particular compact smooth zero-trace functions satisfy The odd-density result after (B15) extends (B20) to compactly supported zero-trace functions in a slightly smaller patch. This extension will be used only after the regularized function has been proved to be .
6. Recovering second derivatives at a flat boundary
Assume the principal coefficients in (B16) are Lipschitz, the frozen principal polynomial is real elliptic, and the lower-order coefficients are locally bounded. If then for every , Here may meet the boundary plane. Merely knowing the interior theorem would not establish this assertion.
Proof. Choose equal to one near , put , and extend tangentially by zero beyond the patch. The full product rule gives Every derivative on in the displayed sum has order at most one. Its norm is bounded by .
Keep , the original coefficient of , and shrink the patch so that . For each other original multi-index put . These are comparison coefficient functions: the equation and estimate will continue to use the original . The principal are Lipschitz; the lower ones are bounded. All bounds retain their dependence on , , its Lipschitz bound and the original coefficients.
Here is the weak multiplication identity needed before second derivatives are known. For and Lipschitz , define . The weak product rule, tested against compactly supported functions, gives Indeed multiplication by a Lipschitz function is bounded on the test space , so it acts by duality on ; applying the product rule twice gives the displayed terms in their actual order. For , , differentiating makes the entire derivative bracket zero. Thus applying multiplication by to the original weak equation is an exact identity in ; no second derivative has been assumed.
Let be convolution in alone with a compactly supported smooth approximate identity, and put . First derivatives converge in . Every second derivative with a tangential factor already belongs to , since that factor may differentiate the smooth convolution kernel and the remaining derivative falls on . Tangential convolution commutes with distributionally. Consequently (BO2) and the complete original equation yield All sums in this proof range over the original . For a principal , write with tangential. Apply Section 7 of Local inverses and distance-weighted elliptic estimates to at fixed . It gives The Lipschitz and convolution bounds are uniform in . More explicitly the commutator is bounded by a fixed constant times ; for almost every it tends to zero. The square of this dominating function is integrable, so dominated convergence proves the displayed full-space convergence. For a lower-order term put . The exact difference tends to zero in using only boundedness of . Define Thus the actual original operator, with its full coefficient, satisfies This identity and the already known nonnormal second derivatives express as an function. Multiplication by the retained proves , and hence , before (B20) is invoked. Its trace is zero because tangential convolution commutes with the continuous trace; its support lies in a fixed compact subpatch for small .
Apply the original estimate (B20) to , using the odd-extension density after (B15). Formula (B24), with (BO4) and every commutator retained, makes the right side tend to zero. Completeness gives an limit, and the convergence identifies it with . Testing against compact smooth functions identifies all second-derivative limits with its distributional derivatives. The same estimate gives (B22), with constants containing the coefficient and reciprocal bounds already stated. For , there is no tangential convolution: the original equation is , whose right side is . Its actual nonzero coefficient gives , and (B20) applies.
7. Smooth bootstrap and a single inverse on all integer scales
Suppose the coefficients are smooth on a neighborhood of the closed flat patch and retain the ellipticity condition above. For every integer , a zero-trace solution initially in , with , satisfies on a smaller patch The nested patches used in the proof may depend on ; the solution does not.
Proof. The case is (B22). Inductively suppose on the required local patches. For a tangential with , the original differentiated equation is The right side is : at least one derivative in each commutator term falls on the original coefficient, leaving at most derivatives on . The function belongs to , and its trace is zero by (B4) and approximation. Applying (B22) on nested patches gives all derivatives of total order having at most two normal factors.
Retain and the complete original equation in the form For a target derivative with normal factors, write it as , where and . The full differentiated identity is In the first sum the terms with have at most normal factors. Every other term on , including every differentiated original normal coefficient in the last sum, has total order at most . Increasing induction on , beginning with the tangentially obtained orders, therefore makes the entire right side . The weak identity (BO2), or its smooth coefficient version, allows multiplication by the actual , which supplies precisely the target derivative and its norm bound. None of the derivatives of in (BO6) has been removed. Cutoffs between and , the full product formula (BO1), and preceding-order estimates control all localization terms. There are finitely many multi-indices at each order, proving (B25) with its stated finite constant.
There is, in addition, one local inverse acting on the whole half-space, whose higher-regularity property holds for all such integers. Choose a patch on which (B17) is constructed, a smaller , and smooth cutoffs with compact support in , where near and near . With the inverse on , define The cutoff vanishes near the artificial boundary, so the indicated extension is bounded into . On , and its trace is zero. If has zero trace, then , so (B17) gives on . Finally (B25), applied on a neighborhood of , gives The operator in (B27) is fixed before is chosen. Global half-space boundedness and the local inverse identities are separate statements.
8. Global regularity of the energy solution
Under the assumptions of Section 3, suppose now that is and the coefficients are Lipschitz on . Then the solution of (B10) satisfies If the coefficients, boundary, and forcing are smooth up to the boundary, then .
Proof. On an interior patch, expansion of divergence form gives . The second sum is , since its coefficients are bounded almost everywhere. The interior theorem in Section 8 of Local inverses and distance-weighted elliptic estimates applies to the principal part with , giving a local bound in terms of .
In a boundary patch use a flattening . Weak chain rules were proved in Section 2. The transformed principal coefficient matrix is obtained by multiplying on its two sides by the inverse derivative of ; it is real positive definite, uniformly so on a smaller compact patch. Its entries are Lipschitz: is Lipschitz, and the first derivative of the diffeomorphism and its inverse are Lipschitz on that patch. The additional first-order coefficients involve first weak derivatives of and weak second derivatives of , and are bounded almost everywhere. One can first transform the divergence-form weak identity by change of variables and then expand it; this justifies the computation for without assuming second derivatives. The Jacobian and its inverse are bounded. The trace is zero by the characterization after (B6). Thus (B22), including its bounded-lower-coefficient case, gives the desired local estimate. Here are the weak chart details needed at this lower boundary regularity. Locally the boundary is a graph with ; take On each fixed compact patch are bounded and Lipschitz, and every weak second derivative of either map is bounded. A general fixed rigid change before this graph map retains these properties and its actual Jacobian. The composition result in Section 2 applies, since these are diffeomorphisms. For a smooth function , its first composed derivatives are products of with entries of . Applying the Lipschitz weak product rule to these products gives the full formula, almost everywhere, Every term is in , with its norm bounded by a fixed multiple of the norm of on the corresponding patch. Approximate a localized half-space function by the extension and convolution in Section 2. The zeroth, first and second expressions in (BR2) are Cauchy in ; testing against compactly supported smooth functions identifies their limits with the weak derivatives of the composed function. This proves the bounded composition map by as well. The input energy solution needs only the already proved composition until the flattened boundary theorem supplies its regularity.
For clarity, the original divergence-form weak identity transforms with the full coefficient Change of variables in the two first-derivative integrals proves this identity for inputs and tests. Divide by the positive Jacobian to write the transformed distributional equation on coordinate volume. Expanding the divergence uses weak first derivatives of the Lipschitz entries of ; they are bounded. The transformed principal matrix is , and is uniformly positive on the retained compact patch. All remaining terms involve bounded coefficient derivatives, the retained Jacobian derivatives and first derivatives of the solution. The right side is , with its actual volume norm. This proves the nondivergence-form interface to (B22) under , without assuming classical second chart derivatives. After (B22), (BR2) transfers the resulting function back. Thus (B29) includes boundaries and the larger class with the same original operator and energy domain.
A finite cover of the compact closure by these boundary patches and interior patches, with cutoffs, yields . Bound (B10) removes the final term and proves (B29). For smooth data use (B25) in every boundary chart and its interior version, or the same differentiated-equation argument without a boundary. This gives every integer Sobolev order. To conclude classical smoothness, extend each localized function by the integer extension after (B4); for , Cauchy-Schwarz makes , . Fourier inversion and dominated convergence give continuous derivatives through order . Since is arbitrary, smoothness holds up to the boundary.
A boundary with a bounded second weak derivative and no classical second derivative. In a two-dimensional chart take , with the domain above its graph. Then is Lipschitz, and almost everywhere; the second derivative has no value at zero. The graph flattening (BR1) has determinant one and the transformed full negative Laplacian is Both formulas act weakly. The matrix determinant is one and its quadratic form is ; on compact patches it is uniformly positive. Its entries are Lipschitz, and its displayed lower-order coefficient is bounded. Thus this graph satisfies the exact boundary regularity interface although it is not . It is a local chart example; the global theorem still requires the full bounded domain and its complete boundary to be .
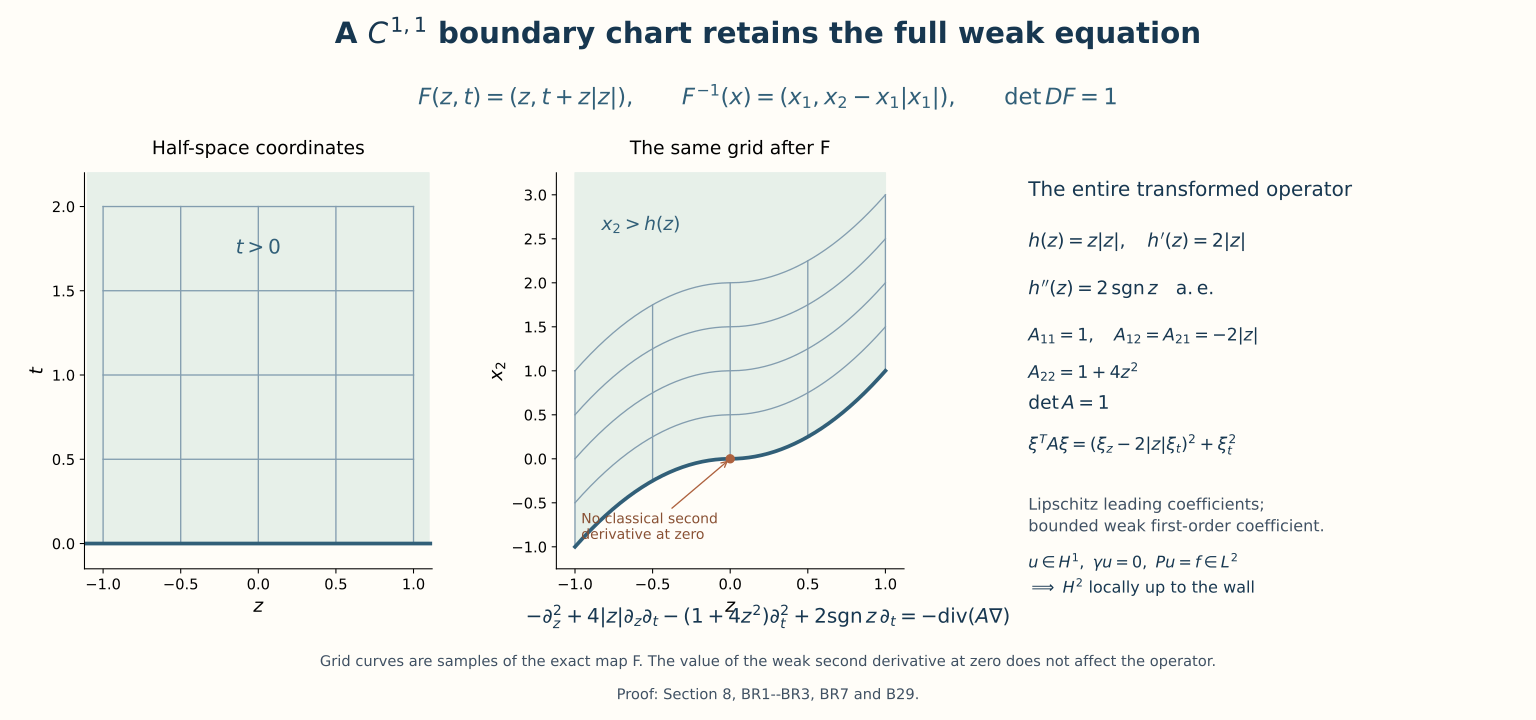
The two graph pieces and the transported grid are numerical samples of the exact formulas (BR1) and (BR7). The weak derivative has values and on the two open sides; its value at zero does not affect the operator. The receiving map is proved in (BR2)–(BR3) and (B29).
9. Complex quadratic symbols and the low-frequency repair
The construction below supplies the complex-coefficient extension of the local Dirichlet inverse and, with smooth coefficients, its simultaneous integer Sobolev improvements. An auxiliary boundary at a fixed positive height removes the low-frequency obstruction. It disappears from the final local assertions.
9.0. Unordered roots, simple-root coordinates and the tangential sphere
We prove the finite-dimensional root and sphere facts before using them in the normal-mode construction. The full factorization theorem, with the original leading coefficient and every multiplicity, is proved in Sections9.1–9.4 of Polynomial and contour tools. Closed bounded finite-coordinate sets are compact by Sections12.6–12.9 of Metric foundations. The actual inverse and implicit maps, including their full remainders and all higher derivatives, are proved in Sections16.4–16.5 of Geometric microlocal calculus. Below we identify the exact polynomial and real derivative matrices to which those proofs apply. No half-plane root count is used to prove its own continuity prerequisite.
The original quadratic, including a repeated root
Let The complex-root theorem supplies a square root of the actual number . When , its square root is zero. If , its two square roots are : any other square root obeys , so one factor is zero. Put To prove the last identity, add and multiply the first two expressions: their sum is , and their product is . Expanding the full last product therefore gives exactly . The original leading factor , both occurrences of a repeated root, and the entire discriminant remain. Changing to exchanges the two entries and changes no unordered pair. When , both entries are the original double root .
For two unordered root lists , , define their distance by Permuting either list exchanges the two candidates, so this is well-defined for unordered pairs with multiplicity. It is symmetric and nonnegative, and it vanishes exactly when the lists agree after a permutation. The triangle inequality follows by composing minimizing permutations for two consecutive comparisons and applying the ordinary complex triangle inequality to each matched entry, then taking the maximum. Thus RC3 is a metric on these unordered pairs. It does not choose a continuous square-root sign or discard repeated roots.
Suppose the original coefficient triples tend to , with . For all sufficiently large , , and has a finite bound . Every root of the actual with satisfies Consequently all roots lie in the fixed disk of radius . List the two roots in nondecreasing order of their original real coordinates and then their imaginary coordinates, retaining repeats. This selects representatives of the unordered pairs; no continuity of the ordering is asserted. Finite-coordinate compactness gives a subsequence on which both entries converge, say to . Passing to the limit in the complete factorization, or in each of its three coefficients, gives Uniqueness of multiplicities in the full factorization theorem says that is exactly the original unordered root pair of . If convergence in RC3 failed, a subsequence would have distance at least some from that pair. Applying the preceding compactness argument to this subsequence gives a further subsequence whose distance tends to zero, a contradiction. This also proves epsilon-delta continuity: its failure would provide coefficient triples within of the original triple whose root distances stay at least one fixed positive epsilon, contradicting the just-proved sequence result. Thus continuity holds at every original coefficient triple with nonzero leading coefficient, including the discriminant-zero locus. An ordered continuous choice was neither assumed nor needed.
The following finite-degree extension is separate from the quadratic entry, and uses the same full factorization proof. For original polynomials keep the degree , leading coefficient and all root occurrences. For , the original root equation gives . The nonvanishing leading coefficient and bounded complete lower-coefficient sum give a fixed disk containing every root. Any sequence of full root lists has a coordinatewise convergent subsequence. In the limit the original identity is . Full factorization uniqueness identifies every limit occurrence with its correct multiplicity. The same contradiction proves convergence in The proof that this is an unordered-multiset metric is exactly the composition-of-permutations argument, with all matched terms retained. A nonzero constant has the empty root list and distance zero; the zero polynomial and a vanishing degree- leading coefficient are outside this theorem. No polynomial is replaced by a monic one.
The exact real implicit map at a simple complex root
Let the coefficients of the original be in the original real parameter coordinates , . Suppose and Write , and apply the real implicit theorem to the actual map . Finite polynomial expansion of the increment in gives its first term and its full higher-order remainder. Thus its actual two by two derivative and inverse at the original point are Both matrix products are the identity by direct multiplication. The denominator is positive by RC8. The unchanged augmented map therefore has precisely the invertible block derivative of IV9 in the independent implicit proof. That proof supplies original neighborhoods and a unique root in the chosen root neighborhood, with . It retains the original coefficient functions, parameter coordinates and Euclidean complex norm; no replacement of by the identity is used.
Differentiating the actual equation gives, in every original parameter direction , This complex formula is the real matrix expression , since RC9 is multiplication by the reciprocal of the actual complex derivative. The full numerator, denominator, signs and all coefficients remain. For the original quadratic the denominator is , and the numerator is .
For clarity, every higher derivative is also governed by the complete original implicit identity. Put . For a finite set of direction labels and , let retain exactly the labels in the nonempty block . In the full labeled-partition chain rule for , the one-block term is , with the complex derivative read in its two real coordinates: the parameter component of is zero for . Hence Both sides of RC11 are read as their original real and imaginary coordinate columns; the inverse coordinate map returns the complex derivative. Every real parameter block, coefficient derivative and repeated-direction multiplicity remains. The chain rule is proved by inserting the next label in an existing block or adding its singleton block; those two possibilities give every new partition once. IV7–IV10 prove the needed smooth inverse and preserve every ordered matrix factor. Thus RC11 is an exact identity at every available order, including coefficients that are only .
Continuous paths on the original tangential sphere
Let and keep the original sphere . For with , the original segment never vanishes on : a zero in the interior would make a negative multiple of , and their original unit lengths would force . The explicit radial map from to the sphere gives the path Its denominator is continuous and positive, so the path is continuous and belongs to the original sphere. If , choose an original coordinate with . Such a coordinate exists because there are at least two coordinates and . The exact vector and its squared length are The vector is orthogonal to , so neither pair , is antipodal. Concatenate RC12 for those pairs: use on and on . Both values at the join are . This constructs a continuous path between every two original sphere points, retaining every coordinate and denominator.
To conclude connectedness, a separation into two nonempty relatively open sets would give a continuous indicator with values zero and one. A path joining a point of each set would give a continuous real function on taking both endpoint values, contradicting the intermediate value theorem at . Thus is connected. The zero-dimensional sphere has its two singleton open components and is not connected; no positive-dimensional argument is applied to it.
Exact use by the original homogeneous quadratic
Return to the original For , neither normal root is real: a real root would give the forbidden nonzero real vector . At a fixed , put , retaining both occurrences. RC3 continuity on an original coefficient neighborhood pairs both perturbed roots within of the fixed ones. Their imaginary signs cannot change. Consequently the number of upper roots, including multiplicity, is locally constant. Composition with any RC12–RC13 path is a continuous integer-valued function on an interval, hence constant by the intermediate value theorem. When , connectedness makes the upper count constant on the entire tangential sphere.
The original odd linear coefficient and even quadratic coefficient give, without discarding any term, The constant count therefore satisfies , so . Each root is simple because one is in each open half-plane. RC8–RC11 apply to the original polynomial at each nonzero tangential frequency. Uniqueness in the upper and lower half-planes makes the smooth local labels agree on every overlap, producing the actual global there.
For , full homogeneity gives The first two identities retain the original , both homogeneous coefficient terms and all powers of . The last follows from their exact root correspondence and the signs of the imaginary parts. The antipodal identities also give and ; the labels are exchanged as required.
On the original compact sphere, define the actual constants Continuity and attained extrema prove the positivity and finiteness: each imaginary quantity is strictly positive everywhere and has an attained minimum. RC16 gives exactly CM1 with these constants, and also . At every multi-index , differentiating the original scaling identity retains the factor , and yields This supplies every original smooth-label derivative with its full frequency power. It makes no assertion of smooth labels through a root collision or through zero frequency.
When , the sphere is . Keep the additional original hypothesis of one root in each half-plane at . RC15 then gives one in each half-plane at , and RC16 handles every nonzero tangential frequency. RC17–RC18 hold on the finite two-point sphere. Ellipticity alone does not supply that hypothesis; the repeated-root example below retains its exact counterexample. When , there is no nonzero tangential frequency and no sphere argument: the original operator is , whose interval inverse is calculated below with the same original . These are precisely the dimensions used by the scalar normal-mode construction.
Precise prerequisites
The finite-dimensional ingredients now have full independent proofs: original complex factorization in Polynomial and contour tools Sections9.1–9.4; unordered root continuity, including collisions and every multiplicity, and exact simple-root implicit coordinates in Section9.0; original finite-coordinate compactness in Metric foundations Sections12.5–12.9; and positive-dimensional sphere paths in Section9.0. The complete root-count and quantitative-separation receiving argument is proved in RC14–RC18 and CM1. The planar extra root condition and the one-dimensional interval case remain explicit.
Use Plancherel and the derivative rule for the Fourier transform on , Fubini and Fatou’s lemma, elementary weak derivatives, and the characterization of integer by square-integrable derivatives. The tangential Fourier normalization may be unitary; using the course convention merely inserts the same factor in both Plancherel integrals. Also use the one-dimensional fundamental theorem for , the trace map proved in Section 2, completeness of /, density of smooth functions for identifying weak derivatives, and the elementary bounded inverse series when . The weak difference-quotient implication used in the smooth refinement is proved below, so it is not an unnamed elliptic regularity import.
Only elementary scalar ODE algebra is needed: a solution of , with distinct roots, is a linear combination of and . This follows either by integrating each first-order equation, or by Sections 1–2 of Stable modes and the algebra of boundary data. No general boundary pseudodifferential calculus, parameter ellipticity, coercive variational theorem, or unproved global inverse for a homogeneous symbol is used.
Root separation at every nonzero tangential frequency
Let be a complex homogeneous polynomial of degree two on , elliptic in the sense
Write
where and are homogeneous of degrees one and two. Assume that, for every , there is one normal root in each open half-plane. Denote the roots by and , their signs referring to their imaginary parts. They are distinct, depend smoothly on , are positively homogeneous of degree one, and for constants ,
Here is why the assumption on root counts is automatic when . On the tangential unit sphere, no root can meet the real axis, by ellipticity. The number of roots in the upper half-plane, counted with multiplicity, is consequently locally constant. One can see this without any chosen labeling: the two roots depend continuously as an unordered pair on the coefficients, and a small perturbation keeps each root away from the real axis. The sphere is connected for , so this count is constant. Homogeneity gives
which exchanges upper and lower root counts. The constant upper count must therefore be one. For , it suffices to check ; the displayed identity gives the same conclusion at , and positive homogeneity handles all other nonzero values. The opposite-half-plane roots are simple, so the implicit function theorem gives their smooth local labels; the sign of the imaginary part makes those labels consistent. Compactness of the unit sphere, continuity of the roots, and the absence of real roots give (CM1).
In dimension one no root-count assumption is needed: , , and CM3 below is simply the ordinary interval Dirichlet inverse with its explicit kernel at .
The half-line kernel and its high-frequency bounds
Fix , put , , and suppress in formulas. For , define
For each fixed , this is continuous at , vanishes at , and solves the homogeneous ODE away from . Its ordinary first-derivative jump is
Since the coefficient of in is , the jump contributes exactly . There is no delta derivative, because is continuous. Thus
The signs in (CM2) are fixed by this jump calculation. For example, if , it becomes
the positive kernel for with zero initial boundary value.
For , differentiating the regular pieces gives
For , this is the bound on the ordinary piecewise derivative; the distributional derivative also contains . Integration in either variable of the right-hand side is at most . The elementary Schur estimate therefore gives
where the delta term is included in the constant when . For completeness, if a kernel satisfies and , Cauchy–Schwarz with measure , followed by Fubini, gives . This is the estimate just used.
Formula (CM5) is a parameter estimate, not an inverse at all frequencies: its zeroth-order bound is . The next step keeps the exact ODE inverse and repairs this low-frequency behavior.
A full inverse on an auxiliary slab
Fix and let . Define
For , the denominator is nonzero: the two exponentials at have different absolute values. At , set and . These are the continuous limits as both roots tend to zero. An explicit nonsingular representation is
For , set
This kernel is zero at both and , and (CM3) still holds with in place of , since the subtracted term solves the homogeneous equation. Its value at zero tangential frequency is
We prove estimates uniform in . If , rewrite
The denominator has absolute value at least , and differentiation gives
Furthermore, (CM4) at , for , gives
Consequently the -th derivative of the correction in (CM8) is bounded by
Its integrals in either variable are at most ; the same holds for the corresponding derivatives of , restricted to the slab. Including the second-derivative delta term yields
For , singular-looking factors can be removed before estimating. On the two triangles in the square, formula (CM2) becomes
Equations (CM7) and (CM12) show that and its ordinary derivatives in through order two, separately on the closed triangles, are uniformly bounded for . They extend continuously to zero frequency and give . The function is continuous and nonzero on the compact tangential ball , including its value at zero. Its modulus has a positive minimum. Thus , its first two derivatives, and the regular derivatives of are uniformly bounded there. Schur’s estimate on the finite square, together with the same fixed delta term in , proves
Combining (CM11) and (CM13), with , gives
For , define by its tangential Fourier transform:
The parameter kernels are measurable, and (CM14) and Plancherel show
Indeed, the three terms in (CM14), squared and integrated in , control all tangential derivatives through order two, all mixed tangential/normal derivatives of order two, and the second normal derivative. The Fourier derivatives agree with weak derivatives by testing against smooth compact functions and using Plancherel; no differentiability of the kernel with respect to is needed. The vanishing endpoint values of the kernels imply zero traces at . This can be checked first after a bounded tangential Fourier cutoff with smooth data in , where the integral formulas are classical, and then by (CM16) and continuity of the trace map. Equation (CM3), applied under the integral first to such data and then by continuity, proves .
Put
The homogeneous equation has no nonzero element of . In fact, the partial Fourier transform of such a solution belongs to for almost every , satisfies the scalar ODE distributionally and has both endpoint values zero. At nonzero , the general homogeneous solution and the nonzero determinant in (CM6) force it to be zero. At , it is affine in , and its two boundary values again force it to be zero. The scalar ODE assertion for an solution follows by applying the first-order integrating-factor identity successively; the result is classical and requires no regularity theorem for PDE. Consequently
In dimension one, (CM9), the derivative jump, and ordinary interval integration prove (CM16)–(CM17) directly. Thus the construction also includes arbitrary nonzero complex .
Exact local inverse identities and small variable coefficients
Let be a bounded neighborhood of a point of , with below height , where and . Extension by zero embeds isometrically in . Define
Then on , on , and is bounded. If is the restriction to of some with , its zero extension from to the slab is in . There are no artificial-side or top-boundary derivative terms: the support is compact in . Nothing is extended through the physical boundary . Hence (CM17) gives the exact left identity
The same model works for the original nondivergence-form variable operator
provided the coefficient suprema on the patch are small enough. One may either use the local Neumann-series argument of Section 5 with , or use the following global slab version, which is useful for the smooth refinement. Extend the to bounded functions on the slab, retaining sufficiently small suprema, and put . If
where is large enough for (CM16) and the component derivative estimates, then . Thus
is a right inverse of . It is also the left inverse on . To see this directly, (CM17) and (CM19) imply
This proves injectivity and the estimate . The difference lies in the nullspace, proving the left identity.
Smallness does not impose extra assumptions on the local theorem. In original coordinates let be bounded near the origin, with the second-order coefficients continuous there, and let satisfy CM1. Set , multiply the equation by , and work in a fixed-size -patch. The coefficient differences are
Their suprema tend to zero on that fixed patch. Multiplying by a fixed cutoff, equal to one on a smaller patch, extends them to the slab with the same small-supremum property. Applying (CM20) and rescaling back proves the original local inverse statements, with constants allowed to depend on the chosen neighborhood. If the coefficients are merely bounded/continuous, this argument gives exactly the statements; it does not claim higher regularity from those assumptions.
One inverse with every integer smoothness improvement
Assume now that the coefficients are smooth on a neighborhood of the closed local patch. In (CM22) take the cutoff inside that neighborhood. The extended coefficients are smooth on the closed slab and all their derivatives are bounded. They continue to satisfy (CM19). The same from (CM20), chosen once at the level, satisfies
Here are the details, including why no new inverse or new smallness condition is required when increases. Write . For a tangential coordinate , let and . Tangential translations preserve . If has one tangential derivative in ,
This is simply the difference rule for each product; the constant coefficients of have no difference term. For each fixed nonzero , , so (CM21) applies. The fundamental theorem of calculus bounds by , and bounds by . Consequently is uniformly bounded in .
To justify the passage to a weak derivative without inserting a compactness theorem, put for . The uniform bound just proved gives a uniform bound on . Tangential Plancherel and Fatou’s lemma imply
The inverse tangential Fourier transform of is therefore an function; testing the Fourier derivative rule against smooth compact functions identifies it with the weak derivative . Applying this for all proves and the same norm bound. Its two boundary traces vanish: in the partial Fourier description, tangential differentiation multiplies the endpoint trace by ; the original trace is zero. Equivalently, extend the distributional tangential derivative identity to the continuous trace map. Thus .
Repeat this argument for tangential derivatives. For a tangential multi-index , differentiating the equation in the sense of distributions gives
Suppose all tangential derivatives through order already belong to , and . For , the right side of (CM25) has each first tangential difference quotient uniformly bounded in : the derivative of exists because ; when a difference falls on , its required tangential order is , already known. Coefficient derivatives are bounded. Apply (CM24) to the equation for , then the same weak-derivative argument. Induction proves
This controls every derivative with at most one normal differentiation and total order at most , as well as the derivatives with two normal differentiations and at most tangential differentiations. To obtain the remaining derivatives, write the equation as
where is the coefficient of in . Shrinking the initial coefficient bound if needed ensures ; this is one fixed bound at the original construction stage. All derivatives of and are bounded. Apply a mixed derivative of total order at most to (CM27) and expand products. Any derivative of then has order at most . In every term containing , the normal order is strictly smaller than the target normal order, and total order is at most . Induction on normal order, starting with (CM26), proves that all these weak derivatives exist in and obey (CM23). Product differentiation is valid distributionally and all products obtained are , so this also verifies each induction step without presupposing the sought regularity. For , the same induction starts directly from (CM21), with no tangential step.
Finally convert the slab inverse into the globally bounded half-space operator used in the local theorem. Choose equal to one on a neighborhood of the chosen local patch, with support below height . Restrict their products to , and define
extending the result by zero from the slab across its top into the rest of . Because vanishes in a neighborhood of the top, this extension preserves every integer Sobolev order. Multiplication by these fixed smooth cutoffs is bounded on each . Hence
The trace of at the physical boundary is zero. On the local patch where both cutoffs are one and , equation (CM20) gives . For a smooth compactly supported local input with zero physical trace, its slab extension lies in , , and ; therefore on the patch. These are local inverse identities, while (CM29) is global half-space boundedness. If the coefficients were first rescaled, undo the dilation as in (CM22); the same assertions hold in the resulting smaller original patch.
No arbitrary global right inverse for the original variable-coefficient operator is claimed. The coefficients away from the patch and the auxiliary top boundary serve only to construct one bounded local inverse with the stated support and regularity properties.
A diagnostic example
The exceptional planar root condition is necessary for the decaying half-space Dirichlet model. Take
This is elliptic on real nonzero : can vanish there only at the origin. At positive , however, both roots lie in the upper half-plane. Choose a nonzero and define a half-space function by
Every derivative through every finite order is square-integrable, the trace at is zero, and . The last identity follows because , which the same first-order factor kills. Thus the half-space nullspace with zero Dirichlet data is nontrivial. The root count in CM1 cannot be silently removed when .
Scope of the complex quadratic model
Here the auxiliary slab inverse controls both low and high frequencies. Difference quotients then prove smooth regularity for that same fixed inverse, so the construction and its regularity estimates use one operator.
Gerd Grubb’s Chapter 9, Boundary value problems in a constant-coefficient case treats half-space Fourier methods and the Dirichlet model. That inverse is narrower than the arbitrary homogeneous complex quadratic polynomial proved here and does not supply the zero-frequency slab estimate. The Fourier and Sobolev prerequisites are proved in Sections 1–2.
The formulas (CM1)–(CM29) prove the scalar quadratic assertion and the smooth inverse refinement. They do not prove the higher-order system or boundary-operator cases, which require separate arguments.
The proof in Section 6 also applies when the frozen quadratic is complex and satisfies the root condition of (CM1): replace the reflected model estimate by (CM16)–(CM21), and use the same odd-extension density for compact zero-trace functions. That density concerns the function space, not commutation of a complex mixed-term operator with reflection. Keep the actual nonzero coefficient: CM27 retains its original inverse multiplying the complete bracket, including every original coefficient and source term. The full reciprocal derivative formula in Section9.1 of Symbols, operators and Sobolev scales supplies all derivative factors; no leading coefficient is discarded. Equations (BO1)–(BO6) give the weak multiplication map, the full original-operator commutators and every normal coefficient derivative; the same reconstruction applies here. Thus no real-coefficient assumption is reintroduced into this extension.
10. Setting, conventions, and the exact analytic inputs
Let , , be bounded with smooth boundary . Neither nor its complement is assumed connected. A smooth boundary means a compact embedded hypersurface with a smooth collar, with on one side. Compactness provides finitely many charts and finitely many connected components. Let always point out of . A superscript minus denotes the trace from , a superscript plus the trace from its complement; both normal derivatives use this same . Write , and fix Then . Indeed is harmonic off zero and its outward flux on every centered sphere is one. Integration by parts outside a shrinking ball, with the test function replaced there by its value at zero plus an error of size , proves the distributional assertion. The flux-one normalization is the sign convention used throughout.
The following inputs are precise dependencies, not layer-potential assertions assumed in advance.
- Traces and lifts. On a bounded smooth domain, is bounded and onto with a bounded right inverse, , smooth functions are dense in these spaces, and localization in smooth collars preserves these facts. Surface Sobolev spaces have the chart norms of Section 11 of Detecting regularity without choosing coordinates. The trace on both sides of a hypersurface agrees for a function in ambient .
- The harmonic Dirichlet solution. The variational harmonic Dirichlet solution exists uniquely for each , with . Smooth data produce a smooth solution up to the boundary, continuously in every smooth seminorm. The local version holds for smooth inhomogeneous equations in a collar, including collars in a complementary component. The preceding Sections 2–3 and Sections 7–8 supply the exact proofs; their use is detailed immediately below.
- The energy identity. Weak Green integration by parts, the divergence theorem for smooth functions, and the fact that a function with zero weak gradient on a connected domain is constant. For a harmonic , its weak outward derivative is the functional , where . The functional is independent of the extension by harmonicity and the trace facts, and belongs to .
- Section 5 of Finite defects under perturbation supplies the compact-perturbation Fredholm theorem. Sections 1–6 of Detecting regularity without choosing coordinates and Section 11 of Detecting regularity without choosing coordinates supply the ordinary classical calculus, its coordinate transport, elliptic parametrices, and all real Sobolev mapping estimates. Section 11 of Singularities along a submanifold and smooth boundary passage and Section 13 of Singularities along a submanifold and smooth boundary passage supply coordinate-invariant ordinary transmission and the boundary symbol of a simple or differentiated layer of an integer-order classical operator. We use these only for the Euclidean Laplace inverse and its smooth coordinate transports; this part asserts no result for an arbitrary symbol family or system.
The analytic dependencies have concrete proofs earlier in this lesson. Section 2 proves the trace facts, including a bounded lift in charts and the zero-trace characterization. For the harmonic Dirichlet solution, lift the datum to , and apply Section 3 to the zero-trace equation , that is, ; the resulting is harmonic, unique by the energy identity, and obeys the stated norm bound. For smooth data choose the smooth lift supplied by the same construction; Sections 7–8 then give all integer estimates for , hence smoothness and continuity in smooth seminorms. Their localized versions give the collar assertion. The energy identity uses the weak integration identities in Sections 2–3. Thus these are exact adapters to those earlier proofs, not an imported harmonic Dirichlet theorem. A locally integrable function with zero weak gradient is constant on each connected component: convolution on a ball makes it a smooth function with zero gradient, hence a constant there; convergence of the convolutions identifies its distributional value, and overlapping balls equate these constants throughout a connected component.
The elementary distribution operations, Fourier inversion/Plancherel, finite-dimensional calculus, integration, and smooth manifold assumptions are those already declared in Singularities along a submanifold and smooth boundary passage and Detecting regularity without choosing coordinates. The uses of compactness in this part are on the compact hypersurface , not on an arbitrary noncompact boundary.
11. Boundary kernels gain one derivative
For smooth densities set, at points off , They are harmonic off , by differentiating the smooth kernel on every compact set separated from . Their boundary operators are These integrals are ordinary locally integrable integrals for smooth densities, not unspecified principal values. In particular is the adjoint of for surface measure; is selfadjoint. This follows first by Fubini after absolute integrability, then by duality on Sobolev spaces.
Here is an explicit regularity argument. In a boundary chart , , put . Taylor expansion gives The second estimate also holds with the normal evaluated at . Both are uniform with differentiated Taylor remainders on compact chart subsets. For , each localized kernel in (LP3), including the surface Jacobian, therefore satisfies To see that this is a symbol estimate of order , split a cutoff kernel into annuli , . Its Fourier transform , differentiated times in , has the bound Indeed its support has volume ; each factor gives , and integration by parts in supplies the last factor after rescaling to a fixed annulus. Summing separately over and its complement, choosing , gives . The off-diagonal part is smooth. Thus all three operators belong to .
There is a small dimensional detail when . In a curve chart, . The squared norm of the last integral is smooth and positive. Hence the single-layer kernel is a smooth coefficient times , plus a smooth function. Its leading coefficient is the boundary arclength Jacobian. The Fourier transform of a cutoff has leading term : differentiate once, use the principal-value transform , and divide by away from zero. That transform follows directly by regularizing the odd integral with , integrating its sine part, and letting . Taylor expanding the smooth coefficient at , or differentiating this Fourier formula, gives the successive lower orders; the Taylor remainder is controlled by the annular argument with its extra powers of . For , the numerator in (LP4) is times a smooth function and the denominator is times a positive smooth function. Those localized kernels are smooth. Consequently are in fact smoothing on a smooth planar boundary. The weaker order conclusion remains valid in every .
We also need the precise leading symbol of , not just its order. Write the Laplace inverse near the diagonal as the classical Fourier operator with high-frequency symbol , plus a smooth kernel. The difference is smooth because applying to it gives the inverse Fourier transform of a compactly supported smooth function; equivalently its Fourier transform is supported at low frequencies up to the fundamental-solution ambiguity, and its derivatives are smooth. In normal coordinates its principal symbol is . The integer parity gives ordinary transmission in both directions, and Section 11 of Singularities along a submanifold and smooth boundary passage preserves this after a smooth chart change, including the surface-density factor in the layer. Section 13 of Singularities along a submanifold and smooth boundary passage, or its absolutely convergent normal integral in this case, yields The same theorem gives all homogeneous remainders, so is classical and elliptic of order . It also gives classical order zero for the one-sided double-layer trace; after subtracting the jump in Section 12 its order-zero symbol vanishes, consistently with the directly proved order bound for . Smooth low-frequency choices do not change any of these symbols.
For every real , therefore, The continuity is precisely the order case of Section 11 of Detecting regularity without choosing coordinates. For compactness, localize to finitely many charts supported inside coordinate cubes and regard their zero extensions in a larger torus. Fourier truncation to has finite rank, while its tail has norm at most . Multiplication and coordinate transport are bounded. Combining these finite-rank approximations through a finite partition proves the compact embedding used in (LP8), for negative as well as positive .
12. Which half of the identity occurs
For smooth densities the four traces are The last equality uses the same vector on both sides.
We give the limiting details. Fix a boundary point, rotate its tangent plane to , and write the boundary as , with , the domain locally below the graph, and outward normal upward. Approach along , . The leading part of either the double-layer kernel or the normal derivative of the single layer is, respectively, Their integrals over the entire tangent plane are and . One way to calculate the constant is to map the plane radially to the corresponding hemisphere: is its solid-angle measure. The kernels concentrate at zero, and their integrals outside a fixed disk tend to zero. Replacing a smooth density by its value at zero therefore gives precisely the indicated half jump.
Curvature has an integrable limit. With , the boundary height is and its derivatives have the corresponding Taylor bounds. Subtracting (LP11), the errors due to numerator, Jacobian, and denominator are bounded, on a small disk, by . For example the denominator difference has numerator bounded by ; after multiplication by the flat numerator , division by one additional reduces it to the same bound on a sufficiently small disk. Its integral on is at most , uniformly in , since . Terms multiplying the difference of density from its value at zero have flat-kernel integral bounded by on a fixed disk and hence tend to zero. Outside that disk the kernels converge with every derivative. Let first and then . What remains is exactly the integrable boundary kernel or . Approaching from the other side reverses the sign of (LP11). This proves the double-layer and single-normal formulas.
For itself, the integral on a boundary disk of radius is uniformly if , and if . The complementary integral converges smoothly. Thus its trace is continuous across the boundary and equals . The smooth one-sided boundary regularity follows either from the integer transmission input or, once the smooth traces have been identified, from local smooth Dirichlet regularity. This also justifies the distribution calculation for the remaining normal trace.
Explicitly, for a piecewise smooth function harmonic on both sides, put and . Integrating twice by parts gives But , so . By (LP9), . Comparing (LP12) proves . It also confirms , independently checking the signs in (LP10).
As a useful normalization check, the divergence theorem applied to (LP2) gives in and in its complement. Thus . On a flat boundary the curvature kernels vanish. Accordingly has Dirichlet trace the identity, while has outward Neumann trace the identity. These are the two normalized half-space constructions.
13. Energy traces and Green representation
All formulas needed for the boundary problems extend at the energy exponents: where the second local space includes bounded collars on the exterior side. No decay or global assertion at infinity is included for .
For the first map, the trace facts and duality give : pair it with an ambient function and take its trace. The high-frequency multiplier maps to , directly from its weighted Fourier bound. Its difference from is smooth, and convolution with a distribution supported on compact gives a smooth function on every fixed compact set, with seminorms bounded by the density norm. This proves the first assertion. Its trace is , by smooth approximation and the trace facts; its weak normal traces are (LP10), by the bounded weak Green functional. This argument works at itself, with no hidden loss.
For smooth harmonic , Green’s formula on proves Indeed the integrand on the outer boundary is ; its integral equals the value , since the inward-facing small sphere contributes . The term with on that small sphere tends to zero: its bound is in and in . More invariantly the corresponding identity in the whole space is It follows from and the identity for compactly supported distributions . The latter follows by moving the derivatives in convolution onto , where .
Define the Dirichlet-to-Neumann map the harmonic Dirichlet solution and the weak normal estimate prove boundedness. For smooth , (LP15) applied to says . The already proved single-layer bound consequently gives the second assertion of (LP13) for smooth , uniformly in its norm. Smooth approximation extends uniquely and proves (LP15) for every harmonic , because such a equals . In particular the jump relations now hold as bounded maps into or , at exactly the indicated energy spaces.
For , Thus is symmetric in the Sobolev duality, and its kernel consists of traces of functions constant on each connected component of . This is not a claim that the layer density kernels are always identified injectively with those constants.
The compatible energy Cauchy pairs are exactly Necessity is Dirichlet uniqueness; sufficiency is the solution . For an arbitrary pair the potential is harmonic and has interior trace . Its interior normal trace is , which need not be . The bounded map is a projection onto (LP18): (LP14) makes it the identity on that graph. A pair is therefore compatible exactly when it is fixed by . Merely substituting arbitrary two boundary functions into a representation formula does not prescribe both traces.
14. Fredholm equations with their actual defects
For the normalized Dirichlet ansatz , the density equation is For the normalized Neumann ansatz , it is Both operators are identity plus compact, hence Fredholm of index zero. The same statement holds on for every real . A kernel vector is smooth: its equation expresses it as an order-minus-one operator applied to itself, and iteration raises its Sobolev order arbitrarily. The identical argument makes every cokernel distribution smooth. Fredholm solvability is therefore an actual finite list of smooth dual orthogonality conditions, independent of the exponent, not an assumption of invertibility.
The defects can be identified topologically. Let be the connected components of . Then Here each indicated function is constant on every boundary piece belonging to that component, and zero on the others. For the inclusion from right to left, the divergence theorem gives . Conversely, if , the exterior trace of vanishes. On each bounded complementary component, Dirichlet uniqueness makes the potential zero. On the unbounded component it is zero as well: , , as follows directly by differentiating (LP2) for larger than twice the diameter of . Integrating its energy in a large truncation gives an outer boundary term . Its normal derivative is continuous by (LP10), so the interior derivative is zero. Applying the interior energy identity makes constant on each , and its interior trace is . This proves (LP21).
Adjointness, closed range, and index zero now imply The pairing is distributional when . At , (LP20) and (LP13) therefore solve every compatible harmonic Neumann problem. Every two solutions differ by a constant on each , by the energy identity. Conversely those compatibility conditions are necessary by testing the weak Green identity against . The statement applies even when one component of surrounds another; no connected-complement assumption was used.
The double-layer defect is different. Let be the bounded connected components of , and let equal one on all parts of adjacent to , zero elsewhere. A complementary component can itself have several boundary components, for example when there are nested islands. Then Indeed the normal out of is , so away from the surface. For the converse, a kernel vector gives a double layer zero in . Normal continuity gives zero Neumann data in every complementary component. Its energy makes the potential constant on each bounded and zero in the unbounded component, using the same decay estimate as above. The value jump then gives exactly (LP23).
Thus (LP19) is invertible if the complement has no bounded component. If there are holes, it has kernel and cokernel dimension , and its exact range is This is a finite-dimensional obstruction of the pure double-layer representation; it does not obstruct the Dirichlet problem itself. The harmonic Dirichlet solution and (LP14) always give the harmonic solution and its combined representation . If a single density equation without compatibility conditions is desired, one must add a finite-dimensional correction, rather than silently discard (LP24).
15. The logarithmic constant and two diagnostic calculations
Changing in (LP1) adds a constant to . It changes and by the rank-one operation which multiplies by that constant; it changes neither , , , nor the two density equations. In dimension two, for smooth , with the differentiated expansion obtained directly from (LP2). Thus decay at infinity cannot be assumed for a general single layer. No such assumption entered (LP22).
For a circle of radius , the constant density has in the disk. To compute this, average for : the real part of the convergent series for has average zero. In particular makes a nonzero density have identically zero interior potential. The interior normal derivative is zero for every , so regardless. The proof of (LP22) used the adjoint equation, and did not make the false inference that the map from kernel densities to interior constants is injective. Ellipticity of in (LP7) also does not mean that itself is invertible.
For the annulus , a density equal to constants on the two spheres has in the annulus. The inner sphere is oriented into the hole, and its double layer is zero outside that sphere. In the ordered constant-density basis (inner, outer), The harmonic function taking different constant values on the two boundary spheres is not a pure double layer. To see this without restricting the unknown density to constants, average any proposed representation over rotations: the kernel and the domain commute with rotations, while those boundary data are invariant. Its averaged density is constant on each sphere, contradicting the first calculation. The harmonic solution is an affine function of for , or of for . This example separates failure of an ansatz from failure of a boundary problem.
16. The Dirichlet-to-Neumann symbol without an assumed layer inverse
The map in (LP16) is a classical pseudodifferential operator of order one on , and Here is a proof which retains possible kernels of . Trace (LP14) to obtain On smooth data, symmetry of and adjointness of give . By (LP7) and Section 6 of Detecting regularity without choosing coordinates choose a right parametrix such that with smoothing. Then, on smooth data, The error is a smoothing operator: maps distributions continuously to smooth functions, and the harmonic Dirichlet solution together with normal differentiation makes continuous. More explicitly, apply in the output variable of the smooth kernel of ; continuous parameter differentiation shows that the resulting kernel is smooth in both variables. Thus (LP29) also defines an extension to all distributions. The product term is classical by the previously specified calculus, and its principal symbol is . It agrees with the energy-defined by density. This proves (LP27), all mappings , and its elliptic regularity at every real , without assuming invertibility of or imposing a normalization in dimension two.
17. Removing every higher normal derivative
Use inward distance in a collar of , so that at . The Euclidean metric has the form , and the Laplace equation reads This follows directly by applying the divergence formula for the metric to the gradient; the mixed terms vanish because distance curves meet parallel surfaces orthogonally.
Set , , , where . There are tangential differential operators , with , , such that The zero operators are assigned every upper order bound. Start with and . Differentiating (LP30) times in gives the exact recurrence Substitution of the earlier proves (LP31) by induction. Multiplication by has order zero; has order at most two. The displayed order bounds follow term by term. Formula (LP32) retains all curvature and normal coefficient derivatives; replacing it by its flat principal part would not prove the exact reduction.
Let be a scalar differential boundary operator of order at most , , with arbitrary smooth complex coefficients. In a collar, express it with coefficients to the left as , where . Equations (LP31)–(LP32) produce the exact identity on smooth harmonic functions For , . On overlaps the formulas describe the same operator on the boundary jets because they were obtained by equality with the given differential operator and the intrinsic equation. A partition of unity consequently yields global tangential operators. For arbitrary energy harmonic functions, the right side of (LP33) defines a distribution in ; it agrees with the classical boundary operator whenever the original traces exist, in particular for , , by the approximation argument below using the following trace bound. For an ambient extension, Fourier inversion in the normal variable and Cauchy–Schwarz bound its normal-derivative trace of order by the square root of , where . This integral is finite exactly when . Integrating with the boundary weight proves the bound. The corresponding slice maps are continuous down to the boundary by the same estimate and density; an extension zero on the interior side consequently has zero trace, proving independence of extension. Quotient norms, smooth coordinate transport from Section 11 of Detecting regularity without choosing coordinates, and a finite chart partition give the asserted domain trace bound. It does not assert a classical high normal trace of every function.
To justify the approximation for , take restrictions of smooth approximations to a fixed ambient extension of . Then in , while in . For , the differentiated equation has the same right side as (LP32) plus in the recurrence for . Induction therefore expresses the discrepancy in (LP33) as a finite sum of smooth tangential differential operators applied to normal traces of derivatives of , with combined differentiation order at most . The trace bound makes each term tend to zero in , because . The traces of converge in their corresponding spaces as well, so passage to the limit proves (LP33) for the harmonic . For , the identity involves only and , and no residual term occurs. This argument does not require the smooth approximants themselves to be harmonic.
The harmonic boundary problem is therefore precisely with solution for . Its leading symbol is Equivalently, freeze the highest-order coefficients of the original at and apply them to : the result at , with the exponential removed, is (LP35). In the convention , this is . The recurrence has this leading behavior because the frozen equation is . Lower-order terms in (LP32) do not affect it.
For this scalar Laplace equation and one scalar boundary condition, the complementing condition is exactly Indeed the space of decaying solutions of the frozen normal equation at nonzero tangential frequency is one dimensional, spanned by . The boundary map on that space is multiplication by , so bijectivity is precisely (LP36). Compactness of the cosphere makes this equivalent to ellipticity of at the stated order . If the leading symbol cancels, one cannot claim a complementing order- problem merely because the reduced operator happens to have a lower-order elliptic term.
Under (LP36), the parametrix and compact Sobolev embedding imply that is Fredholm for every real . Its kernel and the kernel of its formal adjoint are smooth by the parametrix. Thus its range consists exactly of those data pairing to zero with , and solutions are unique modulo . These finite defects are not asserted to vanish or to have a prescribed index. For each such determines the energy harmonic solution ; Sections 7–8 gives its stronger interior/boundary regularity when applicable. The all-real Fredholm statement concerns the boundary operator and does not assert an unproved low-regularity Poisson mapping theorem.
This argument treats every differential order of a scalar boundary condition for the Laplacian. A system, several boundary conditions, another interior operator, a nonsmooth boundary, or a noncompact boundary requires its own normal solution space, symbol hypotheses, and analytic estimates. Those obligations are not closed by (LP36).
17A. The inward-normal layer system and its effective operator
The introduction to the general boundary theory writes the same Laplace example with the positive Laplacian and the inward normal. We now translate that convention exactly and prove the single-layer inverse used there. This matters because changing the Laplacian and changing the normal each contribute a sign.
Assume in this section that . Keep the exterior normal , the operator , and the fundamental solution from (LP1). Put Let be the single- and double-layer potentials built from and the inward normal . Directly from (LP39), Indeed the double layer receives one minus sign from and a second from . If , , and , then (LP14) becomes
Taking the interior trace and using (LP9) gives or, equivalently, This identifies the chapter notation without hiding a sign in the density. Equation (LP7) gives and .
We still have to prove that is invertible. Suppose first that . Elliptic regularity makes every distributional kernel vector smooth. The function is harmonic on both sides of , is continuous across it, and has zero boundary value. Dirichlet uniqueness makes it zero in every bounded component. On the unbounded component, (LP1) gives The decay suffices for a direct energy proof on the unbounded component, with no maximum-principle input. On its truncation by a large sphere, Green integration gives The boundary pieces on contribute zero because there. The last exponent is the full product from (LP44) and sphere area. For it tends to zero. The left integrals are nonnegative and increase to the integral over the whole component, so that integral is zero. Its weak gradient therefore vanishes, and connectedness makes constant; its decay makes this constant zero. The exact jump in (LP10) is . Both one-sided functions are zero, so both derivatives are zero and . Thus is injective.
The kernel is symmetric. Hence is its own transpose in the boundary duality. It is Fredholm by ellipticity, and its cokernel is the kernel of the same transposed map. Its index is therefore zero. Injectivity now gives surjectivity. Elliptic regularity identifies the kernel and cokernel at every Sobolev exponent with these same smooth spaces, so
To justify the operator assertion in (LP46), retain the right parametrix of Section 16 with . The actual inverse is bounded at every exponent. Indeed let be a left parametrix. If no bound held, choose with in . The smoothing remainder is compact on , by the compact embedding argument in (LP8). A subsequence of converges, and the exact identity makes the same subsequence of converge to a norm-one vector annihilated by , contradicting injectivity. This proves the bound, and surjectivity gives the bounded actual inverse. Multiplying the right parametrix identity on the left by that inverse gives the exact ordered formula These inverses agree on their common domains because distributional injectivity was proved first. The all-exponent bounds and Sobolev embedding make continuous. Applying it to the output variable of the smooth kernel of commutes with every parameter derivative and produces a jointly smooth kernel, by those bounds. Thus is smoothing, and the actual inverse is classical of order one. No inverse of a symbolic formula was substituted for this operator.
This also completes the converse trace argument. If a smooth pair satisfies (LP43), define by (LP41). Its boundary value is . Green’s formula for this actual harmonic function gives . Subtraction shows that in . Its boundary trace is , so injectivity proves .
Let be the outward Dirichlet-to-Neumann operator in (LP16), and set . Equation (LP28) says . Therefore, with the factors in their actual order, For a boundary equation , where both terms have the same target and Sobolev order, (LP43), (LP46), and (LP47) give the exact reduction No factor has been commuted. Since (LP27) gives , If has order and has order at most , the effective principal symbol is The decaying frozen mode in inward distance is , whose inward derivative at zero is . Applying the principal boundary row to that mode gives exactly (LP50). Thus ellipticity of the effective operator is the scalar complementing condition.
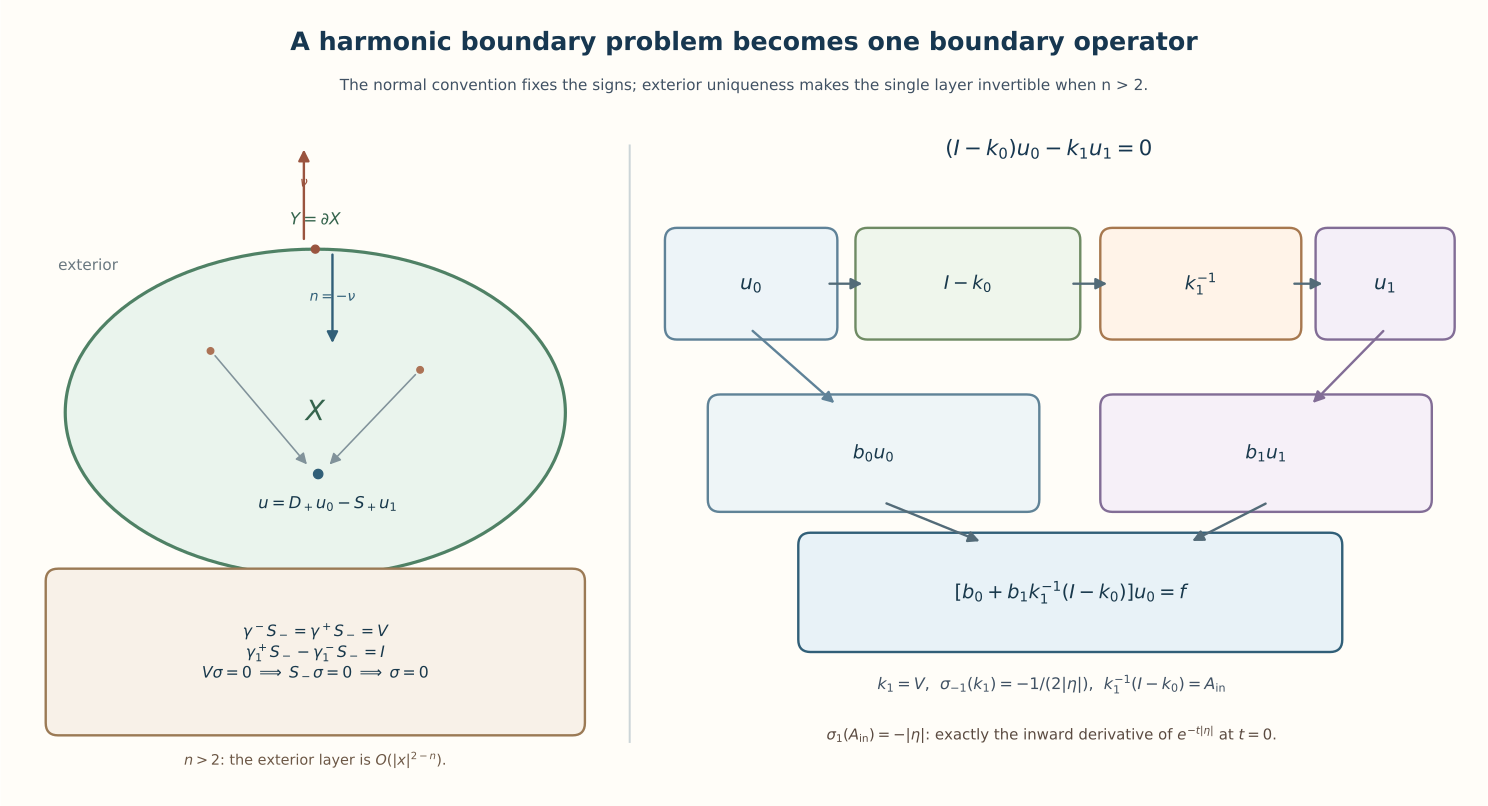
The normal and jump signs are (LP39)–(LP43) and (LP10). The actual inverse and its operator class are proved in (LP44)–(LP46), (BR4) and (BR5); the ordered receiving map is (LP47)–(LP50). The ellipse represents a schematic smooth domain.
The restriction is essential to this particular inverse proof. In dimension two the single layer has the logarithmic term (LP25), changing the fundamental-solution constant changes by rank one, and the circle example can put a nonzero constant density in its kernel. The Dirichlet-to-Neumann construction in Section 16 remains valid there because it used an elliptic parametrix for , not an assumed global inverse.
18. Problems and completed solutions
Problem 1. A compatible pair need not be chosen freely. On the unit disk take and . Can these be the Cauchy data of a harmonic energy solution? What does the potential do when the logarithmic normalization is ?
Solution. Dirichlet uniqueness gives , hence ; the pair is not in (LP18). Independently its Neumann integral is . By the circle calculation inside the unit disk for , so the potential built from the incompatible pair is zero. Its actual Cauchy pair is . Harmonicity of the representation with arbitrary inputs does not make those inputs its traces.
Problem 2. Curvature in a second normal derivative. Let the dimension be and let the domain be a ball of radius . Express for a harmonic function in terms of , , using inward distance .
Solution. Parallel spheres have radius , so , while . Formula (LP30) gives . For , and , so the right side is zero, as it must be because is affine along radial distance curves. Omitting the curvature term would give the wrong answer.
Problem 3. A tangential second-order boundary condition. Consider , with constant . Determine its reduced operator, principal order, and whether complementing alone proves uniqueness.
Solution. Here , , so has order two and principal symbol , regardless of . Thus (LP36) holds. Constants on each component of lie in both terms’ kernels, so uniqueness fails. If , its quadratic form is ; the explicit nonnegative form still has those constants. Ellipticity gives finite defects and regularity, not automatic invertibility.
Problem 4. Count holes, not names of boundary components. Suppose a connected annular region surrounds a second disjoint ball, with positive separation. Count the dimensions of the two density kernels.
Solution. The domain has two connected components, so (LP22) gives , and the Neumann data require two separate zero integrals. Its complement has one bounded component, the region between the surrounding annulus and the inner ball; that complementary region has two boundary components. Formula (LP23) nevertheless gives . Its generator equals one on both boundary surfaces adjacent to this one complementary region. Counting each such surface as an independent hole would overcount the kernel.
For the jump and compatibility comparison, see the Stanford Math 220B potential-theory handout; for a broader Dirichlet-to-Neumann framework, see Gerd Grubb’s Chapter 11, Definition 11.15 and Theorem 11.17. The Stanford notation uses the opposite-sign fundamental solution , then inserts a minus sign in its layers, producing the operators in (LP2). The all-Sobolev proof required here is given above.
19. The zero-dimensional boundary case
If the ambient dimension is one, a bounded smooth domain is a finite disjoint union of intervals . Surface measure is counting measure on their endpoints; use , so again . Every boundary Sobolev space is the same finite-dimensional vector space . For distinct endpoints , the layer matrices are Direct one-sided evaluation of the two sums (LP2) gives exactly (LP9)–(LP10); for example , and its one-sided diagonal contributions are . Green’s formula (LP14) is ordinary integration by parts on each interval. The harmonic extension is affine and the Dirichlet-to-Neumann map is the block matrix This follows by taking its slope , whose outward derivatives at the two endpoints have opposite signs. Neumann data are solvable exactly when their two values sum to zero on each interval; solutions differ by one constant on each interval.
There are no nonzero tangential covectors, so the symbol argument (LP36) is not the appropriate assertion here. Also the higher-dimensional decay used for (LP23) fails: a double layer tends to constants at the two ends of the line. Its interior values are constant on every interval. The densities produce those independent constants, so the Dirichlet trace matrix has rank , kernel dimension , and range the endpoint data with equal values on each interval. Thus the pure double layer again need not represent arbitrary Dirichlet data; the combined representation does. Similarly has rank and range the endpoint pairs of sum zero, by its actual affine single-layer potentials, or by adjointness and .
Every derivative , , of an affine harmonic function vanishes. Hence an arbitrary differential boundary condition reduces exactly to the endpoint values and first outward derivatives. Substitution of (LP38) is the full finite-dimensional reduced problem; its range is the orthogonal complement of the kernel of the conjugate-transpose matrix. No nonempty-cosphere ellipticity condition or higher-dimensional hole count is substituted for this explicit matrix test.
20. Worked diagnostics and problems with solutions
Worked diagnostic: the boundary is part of the functional space. Let . A smooth function supported in and equal to one near zero is an function supported in . It does not belong to : every approximating test function would vanish at zero, and the one-dimensional estimate (B2) on a bounded interval makes point evaluation continuous in . Thus the support description proved for a domain cannot be transferred to arbitrary open sets. The closure definition (B6) continues to make sense.
Worked diagnostic: removing a mixed term before reflection. In two dimensions consider . Reflection across changes the parity of the mixed derivative ; a direct odd-reflection inverse for this unnormalized polynomial would therefore be invalid. Set , . Then , , and substitution gives . The boundary plane and its upper side are preserved, and reflection now applies. This calculation also explains why an arbitrary diagonalizing rotation is not the required coordinate change.
Problem 1. Take nonzero and . Determine which of its zero, even, and odd extensions belong to .
Solution. All three are , and the even extension has derivative , together with the even tangential derivatives, in . Thus it is . Formula (B5) puts in the normal derivative of the zero extension, so that extension is not . The odd extension has jump at zero and hence derivative ; it too fails to be . Odd extension is useful for a zero-trace function, not for an arbitrary boundary value.
Problem 2. On the unit ball in , put , , and . Compute , and identify precisely which global theorem applies.
Solution. Almost everywhere , while all its other weak derivatives vanish. Since , the weak product rule gives . There is no interface delta: the coefficient itself is continuous and Lipschitz. The ball is smooth, , and the matrix is Lipschitz, so (B29) applies with this bounded forcing. The function is already an explicit smooth zero-trace solution and is therefore the unique energy solution by (B10). Its expansion contains a discontinuous but bounded first-order coefficient. This example checks why bounded lower terms were retained in (B22).
Problem 3. Explain why the local left identity in (B17) cannot be replaced by uniqueness of every homogeneous solution in with zero trace on .
Solution. For , the function is harmonic and vanishes on the flat boundary. Its restriction to a bounded patch belongs to , but it is not zero. It has no compact support in the patch. In (B17), the left identity is asserted only for inputs compactly supported away from the artificial sides of ; those support conditions are exactly what justify the convolution identity (B15). Energy uniqueness, when invoked on a bounded domain, uses zero trace on the entire boundary through .
Problem 4. Show that the half-order loss in the trace is quantitatively necessary. Use boundary Fourier transforms supported in a fixed-radius ball around , , and the lift (B4).
Solution. Choose a nonzero smooth Fourier profile supported in the unit ball and put . On this support , so and . The exact integral gives , because any tangential derivative of order two in the first direction has squared integral comparable to . Hence no bound with can hold: the right side tends to zero for this sequence while the left side does not. The same sequence proves the stated sharp trace loss itself: for every , Hence no bounded trace exists. The preceding calculation about lifts proves the separate obstruction to supplying solutions from boundary data of lower regularity. Both statements keep the original profiles, powers and inhomogeneous weights. For , the boundary is zero dimensional and this high tangential frequency example is absent.
Problem 5. Let be harmonic in the unit ball. Can hold on the entire sphere? What is the normal derivative for the Dirichlet value on that sphere?
Solution. Integrating the divergence of gives ; for an energy solution this is the same weak identity tested on the constant function. The integral of the proposed datum one is the positive area of the sphere, so no such harmonic solution exists. For the second datum, is harmonic and has the required boundary value. The exterior normal on the unit sphere is , so . Thus the Dirichlet-to-Neumann operator sends this boundary value to itself. Adding a constant to would change its Dirichlet value and leave its Neumann value unchanged; that is the kernel relevant to the Neumann problem.
Problem 6. In flat coordinates, reduce the third-order boundary condition for a harmonic function on to its two Cauchy traces. Then specialize to a decaying tangential Fourier mode.
Solution. Write and . The equation gives , so and . The boundary equation is . For , one has , and the resulting multiplier is . Its principal homogeneous symbol is , nonzero for . This is a principal-symbol calculation; it does not by itself decide low-frequency solvability or remove finite-dimensional obstructions on a compact boundary.
Further questions and references
The arguments and worked examples needed here are developed above.
John K. Hunter, Notes on Partial Differential Equations, revised 18 June 2014, Theorems 4.9 and 4.11, gives comparison proofs of Poincaré and weak existence. Theorem 4.30 treats boundary regularity with coefficients; the result in (B29) retains Lipschitz leading coefficients. Theorems 4.31 and 4.32 concern higher and smooth boundary regularity.
Three further study routes have precise starting points.
- Beyond the proved boundary class. The weak chart argument (BR1)–(BR3) proves (B29) for boundaries. Going below that class requires controlling the term and the first derivatives of the full transformed coefficient in (BR3). A bi-Lipschitz map alone does not provide either bound. Any further extension must replace those two estimates and retain the actual trace and energy spaces.
- General elliptic boundary systems. The scalar normal root calculation selects one decaying mode. For an operator or system of higher order one must construct the entire decaying solution space, map every boundary operator on it, verify the complementing condition for all nonzero tangential covectors, and solve the constant-coefficient problem with inhomogeneous boundary data in its correct Sobolev orders. The decaying solution space, its boundary maps and the complementing condition are developed in Stable modes and the algebra of boundary data. That lesson retains its stated system and boundary orders. The scalar argument here supplies a concrete model for those constructions.
- Boundary symbols and global defects. Use the harmonic Dirichlet-to-Neumann symbol and the finite-dimensional layer obstructions above as complementary examples. An elliptic principal symbol controls high-frequency inversion; topology and nullspaces still enter global solvability. For the general reduction, first use the coordinate and Sobolev maps in Detecting regularity without choosing coordinates, then the Cauchy spaces in Cauchy data and the Calderón projector, and finally the general operator and data constructions in Reducing arbitrary boundary data to a boundary system.